
How to Calculate Plate Cost: A Restaurant Owner's Ingredient-by-Ingredient Guide
A plate can look profitable on paper until you account for the weight you throw away during prep, the sauce that takes more than the recipe calls for, the garnish nobody measures, and the side that quietly adds another dollar to the ticket. Learning how to calculate plate cost accurately means costing what actually reaches the guest, not simply dividing a supplier invoice by the number of portions you hope to get.
Why a plate that looks profitable can cost more than you think
Imagine a restaurant selling a grilled salmon entrée for a hypothetical $28.00. The chef estimates the fish costs $4.50, the potatoes $0.50, the vegetables $0.75, and the sauce $0.25. The estimated food cost is $6.00, or 21.4% of the selling price.
That calculation looks healthy. But it ignores fish trim, actual edible yield, cooking fat, garnish, and the precise quantities used in the side dishes. Once everything is accounted for, the plate may cost substantially more.
The difference matters because the restaurant isn't buying ingredients at their edible, ready-to-serve weight. It's buying ingredients in the condition the supplier delivers them, then paying for the labor and waste involved in turning those ingredients into a plate.
Start with the actual plate, not the supplier invoice
A recipe costing worksheet needs to answer three questions for every ingredient:
- What quantity did the restaurant purchase?
- What usable quantity remained after preparation?
- How much of that usable quantity went into one serving?
The most common costing mistake is using the purchase price as if every ounce, pound, or piece were usable.
A whole chicken includes bones. A head of lettuce includes damaged outer leaves and a core. A whole fish may include skin, bones, and other material that isn't served. A bunch of herbs may contain stems and wilted leaves. Even a bag of potatoes can produce different yields depending on the preparation.
The purchase unit and the recipe unit therefore need to be connected through yield.
For a consistent worksheet, record the ingredient, supplier purchase unit, invoice price, preparation yield, usable quantity, recipe quantity, and final portion cost.
Calculate edible yield before calculating the portion cost
Yield is the percentage of an ingredient that remains usable for the intended recipe after trimming, cleaning, deboning, peeling, or other preparation.
The basic formula is:
Yield percentage = usable weight ÷ purchased weight × 100
Suppose a hypothetical restaurant purchases 10 pounds of salmon for $120.00. After removing the unusable trim, the chef weighs 8.2 pounds of usable fish.
- Purchased weight: 10.0 lb
- Usable weight: 8.2 lb
- Trim and loss: 1.8 lb
- Yield: 8.2 ÷ 10.0 = 82%
- Purchase cost: $120.00
The restaurant didn't actually receive 10 pounds of usable salmon. It received 8.2 pounds of usable salmon from a $120.00 purchase.
The effective cost per usable pound is:
The effective cost per usable ounce is:
That is the number to use when costing an edible-weight portion.
If the recipe calls for 6 ounces of usable salmon, the fish cost per plate is:
Compare that with the incorrect calculation using the purchase price per ounce:
The restaurant has understated the fish cost by approximately $0.99 per plate.
That difference isn't theoretical. It is money being spent on trim that never appears on the guest's plate.
Use the correct weight basis for every recipe
Recipes can specify ingredients by raw weight, trimmed weight, cooked weight, volume, or count. You need to know which one you're using before calculating costs.
Consider three common situations.
Raw purchase weight: The recipe uses the ingredient as delivered, without meaningful preparation loss. Use the invoice cost per purchase unit.
Edible or prepared weight: The recipe calls for an ingredient after trimming, peeling, cleaning, or deboning. Use the adjusted cost per usable unit.
Cooked weight: The recipe calls for a finished cooked portion. Cooking loss from moisture, fat, or other changes must also be considered if the portion is weighed after cooking.
Don't apply a trimming yield and a cooking yield twice if your recipe's portion weight already accounts for both. The purpose of the worksheet is to establish a consistent path from what you buy to what you serve.
For proteins, I recommend recording both the raw portion weight and the expected finished portion weight. That gives the kitchen a standard for portioning and gives the owner a way to investigate portions that are consistently oversized.
Cost every component of the plate, including the items people forget
The entrée isn't just the protein. Every component that goes out with it has a cost.
For a salmon plate, the worksheet might include:
- Salmon portion
- Potato side
- Vegetable side
- Sauce
- Cooking oil or butter
- Garnish
- Seasoning, where material and measurable
- Any finishing ingredient added at the pass
A few cents of garnish might not seem worth tracking. But if the same garnish appears on several menu items and is used inconsistently, the combined waste can become meaningful.
The same applies to lemon wedges, fresh herbs, flavored butter, dipping sauces, dressings, bread, and other items that are often left off recipe cards.
Use a consistent rule: if it is part of the standard plate, cost it. If it is optional, define when it is included and whether it is charged separately.
Work through a complete plate costing example
The following figures are entirely hypothetical and are provided only to demonstrate the calculation. They are not supplier quotes, industry statistics, or recommended menu prices.
We'll use the salmon entrée above and cost every component.
| Ingredient | Hypothetical purchase cost | Yield | Portion quantity (usable) | Cost per plate |
|---|---|---|---|---|
| Salmon | $120.00 / 10 lb | 82% | 6 oz | $5.49 |
| Potatoes | $30.00 / 25 lb | 90% | 5 oz | $0.42 |
| Broccoli | $25.00 / 10 lb | 80% | 4 oz | $0.78 |
| Sauce | $12.40 / batch | 40 portions | 1 portion | $0.31 |
| Garnish | $8.80 / batch | 40 portions | 1 portion | $0.22 |
| Cooking fat | $9.00 / container | Recipe allocation | 1 portion | $0.18 |
| Total | $7.40 |
Let's verify each line.
Salmon: $120.00 ÷ 8.2 usable pounds ÷ 16 ounces = $0.9146 per usable ounce. Six ounces costs $5.49.
Potatoes: 25 purchased pounds × 16 ounces = 400 purchased ounces. At 90% yield, there are 360 usable ounces. $30.00 ÷ 360 = $0.0833 per usable ounce. Five ounces costs $0.42.
Broccoli: 10 purchased pounds = 160 ounces. At 80% yield, there are 128 usable ounces. $25.00 ÷ 128 = $0.1953 per usable ounce. Four ounces costs $0.78.
Sauce: The hypothetical batch costs $12.40 and produces 40 measured portions. $12.40 ÷ 40 = $0.31 per serving.
Garnish: The hypothetical batch costs $8.80 and produces 40 portions. $8.80 ÷ 40 = $0.22 per serving.
Cooking fat: A measured recipe allocation costs $0.18 per plate.
The total plate cost is $7.40.
At a hypothetical selling price of $28.00:
The plate's ingredient cost is approximately 26.4% of its selling price.
That's different from the earlier estimate of $6.00, which would have produced an apparent food cost percentage of 21.4%.
The restaurant didn't change the selling price or the dish. It changed the accuracy of its accounting.
Turn the plate cost into a menu price without confusing the two
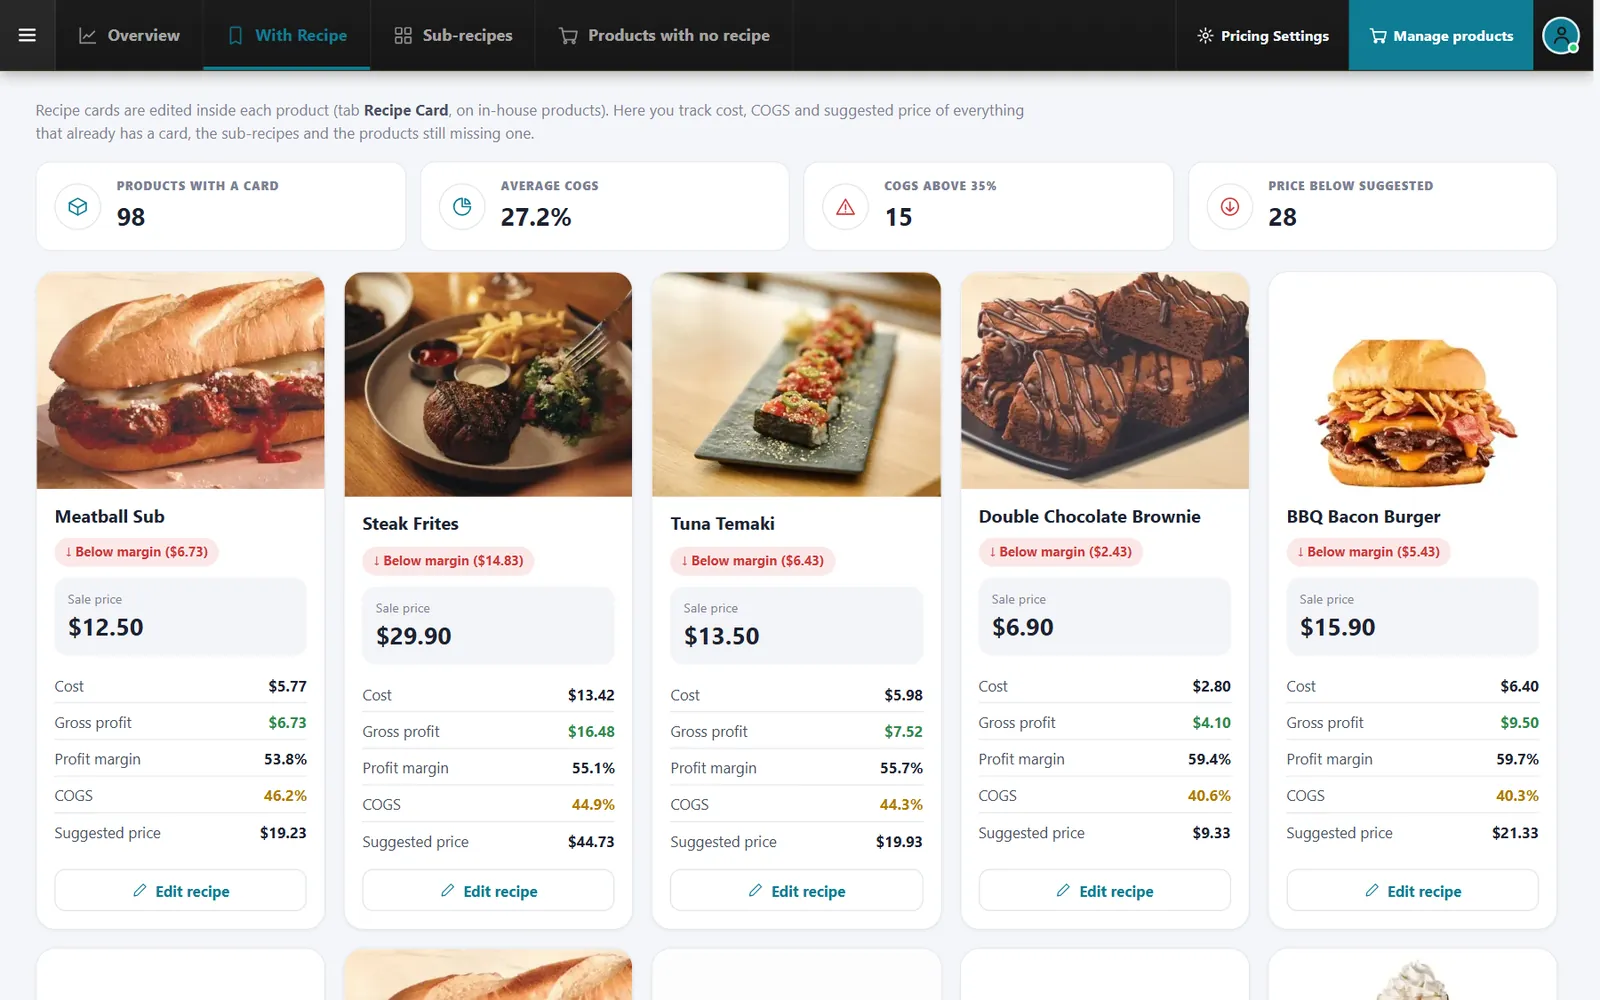
Plate cost tells you what the ingredients cost. Food cost percentage tells you how much of the selling price those ingredients consume.
To calculate the selling price required for a chosen food cost percentage:
For the hypothetical $7.40 salmon plate:
| Hypothetical target | Calculated menu price |
|---|---|
| 25% food cost | $29.60 |
| 28% food cost | $26.43 |
| 30% food cost | $24.67 |
These are mathematical examples, not universal pricing recommendations. Appropriate food cost targets vary by concept, labor model, rent, menu mix, operating expenses, and what guests are willing to pay.
Don't use food cost percentage alone to decide whether a dish belongs on the menu. A dish with a higher percentage can still contribute more dollars toward overhead than a lower-priced dish with a smaller percentage.
At a hypothetical $28.00 selling price, the salmon plate produces $20.60 before other operating costs when you subtract the ingredient cost. That isn't net profit. Labor, occupancy, utilities, supplies, fees, and other expenses still need to be covered.
Build batch recipes before costing individual portions
Sauces, soups, dressings, marinades, braised meats, and prepared sides are easier to cost as batches.
List every ingredient in the batch, convert each quantity into the same unit used for its costing, calculate the ingredient cost, and weigh or count the finished batch into actual portions.
The formula is straightforward:
Batch cost per portion = total batch ingredient cost ÷ actual number of portions produced
Don't use the number of portions the recipe is supposed to produce if your kitchen regularly produces fewer.
If a hypothetical soup recipe costs $48.00 and is expected to yield 24 portions, its planned cost is $2.00 per portion. If the finished batch produces only 21 portions, the actual cost becomes $2.29 per portion.
A three-portion difference changes the economics of every bowl sold.
Use a standard ladle, scoop, scale, or portion container. Then have someone measure the portion during a normal busy shift rather than during a quiet prep session. Portion control needs to survive service.
Keep ingredient costs current when suppliers change prices
A recipe can be perfectly calculated and still become inaccurate when purchasing prices move.
A new invoice might reflect a seasonal adjustment, a different pack size, a substituted product, or a price increase that nobody communicated to the kitchen.
Assign someone responsibility for reviewing supplier invoices and updating ingredient costs. The review should focus first on ingredients that have the greatest impact on the menu.
A practical priority list is:
- High-cost proteins
- Ingredients used across many menu items
- Ingredients with unstable seasonal pricing
- Ingredients with unusually high trim or waste
- Ingredients recently substituted by a supplier
If salmon increases from a hypothetical $120.00 per 10-pound purchase to $135.00 for the same product and pack size, while yield remains 82%, the new usable-ounce cost becomes:
A 6-ounce portion now costs approximately $6.17 instead of $5.49.
The plate increases from $7.40 to approximately $8.08, assuming all other ingredient costs remain unchanged.
At a hypothetical selling price of $28.00, food cost percentage rises to approximately 28.9%.
That is why a menu costing worksheet needs a date, supplier, pack size, and latest verified price. An old recipe card with no revision date isn't a reliable costing document.
Three costing habits worth implementing this week
1. Run a trim test on your five most expensive ingredients
Don't rely on a yield number copied from an old recipe or guessed by the chef.
Take a fresh delivery of the ingredient, weigh it before prep, weigh the usable product after prep, and record the result. Repeat the measurement on another delivery if the result seems unusual.
This reveals whether the yield assumption still matches your actual product and preparation method.
2. Audit the plate at the pass during a real service
Choose one menu item and watch several plates being prepared without interrupting the line.
Weigh the protein, side, sauce, and garnish on a few plates. Record how much each component varies from the recipe. Look for ingredients being added by eye, portions that creep upward, or finishing touches that aren't on the recipe card.
The goal isn't to slow the kitchen down. It's to make the standard portion easier to execute.
3. Create a price-change trigger instead of waiting for the monthly review
Choose a handful of ingredients that materially affect your menu. When an invoice changes, calculate the impact on every recipe that uses the ingredient.
For example, a hypothetical $0.50 increase per portion of an ingredient used in four dishes may affect far more sales than a $2.00 increase in a specialty ingredient used on one slow-moving dish.
The important question isn't just, "What went up?" It's, "Which plates changed, by how much, and what action do we need to take?"
4. Cost the waste bin once a week
For one week, separate avoidable prep waste from unavoidable trim. Record discarded portions, spoiled products, overproduction, mistakes, and food returned from the dining room.
Don't automatically treat every scrap as waste. Some trim can be used safely in stocks, sauces, or other preparations when the recipe and food-safety procedures support it.
This exercise helps distinguish a yield problem from a purchasing problem, a portioning problem, or an overproduction problem.
Use this ready-to-copy plate costing worksheet
Copy this structure into a spreadsheet or print it for your kitchen manager.
| Field | Entry |
|---|---|
| Dish name | |
| Menu selling price | |
| Recipe revision date | |
| Supplier / product | |
| Purchase pack size | |
| Latest invoice cost | |
| Purchased weight or quantity | |
| Prepared usable weight or quantity | |
| Yield percentage | |
| Cost per usable unit | |
| Portion quantity | |
| Portion ingredient cost | |
| Batch yield, if applicable | |
| Garnish / finishing cost | |
| Total plate cost | |
| Food cost percentage | |
| Person who verified portions | |
| Next review date |
For every ingredient, calculate the yield-adjusted cost per usable unit first. Then multiply by the recipe quantity. Add the components together to get the total plate cost, and divide by the menu price to get food cost percentage.
Keep the original worksheet when revising the recipe. It helps you understand whether a change came from the supplier, yield, portion size, recipe, or menu price.
Decide what to do when a plate becomes more expensive
When the worksheet shows that a dish is no longer performing as expected, you have several options. Changing the selling price is only one of them.
Reprice: If the dish is still popular, guests value it, and the market can support a higher price, adjust the menu price. Check how the new price sits alongside comparable items and whether it changes the guest's buying decision.
Rework: Reduce waste, standardize portions, simplify a garnish, or replace a costly component with something that fits the dish and maintains its quality. Test the revised plate before making it permanent.
Renegotiate or source differently: Compare pack sizes, product specifications, and supplier options. A lower purchase price isn't automatically better if it comes with worse yield, inconsistent quality, or additional prep labor.
Remove: If an ingredient is difficult to source, the dish is rarely ordered, the kitchen struggles to execute it, and its contribution doesn't justify its complexity, consider taking it off the menu.
Make the decision using the complete recipe cost, sales volume, contribution dollars, prep workload, and guest experience, not a single percentage.
Use recipe costing alongside the restaurant's daily operating data
Recipe costing becomes more useful when you connect it to what actually happens in the restaurant.
Compare theoretical ingredient usage with inventory usage over a consistent period. Theoretical usage is what the recipes say you should have used based on sales. Actual usage reflects what left inventory, including waste, mistakes, overportioning, and other unrecorded consumption.
If theoretical usage is consistently lower than actual usage, investigate the difference rather than immediately changing the recipe cost.
Check for:
- Incorrect inventory counts
- Unrecorded staff meals
- Waste and spoilage
- Portion sizes exceeding standards
- Ingredients used in dishes without a recipe
- Supplier pack sizes or invoice prices entered incorrectly
- Sales that don't reflect modifiers or substitutions
A recipe costing system can show the expected cost of a dish. Your inventory and sales records help you determine whether the kitchen is operating close to that expectation.
Keep recipe costing organized as the menu changes
For a small restaurant, the process doesn't need to become an administrative project. A weekly review of key invoices, a monthly review of recipes, and a documented update whenever a significant ingredient changes can keep your numbers useful.
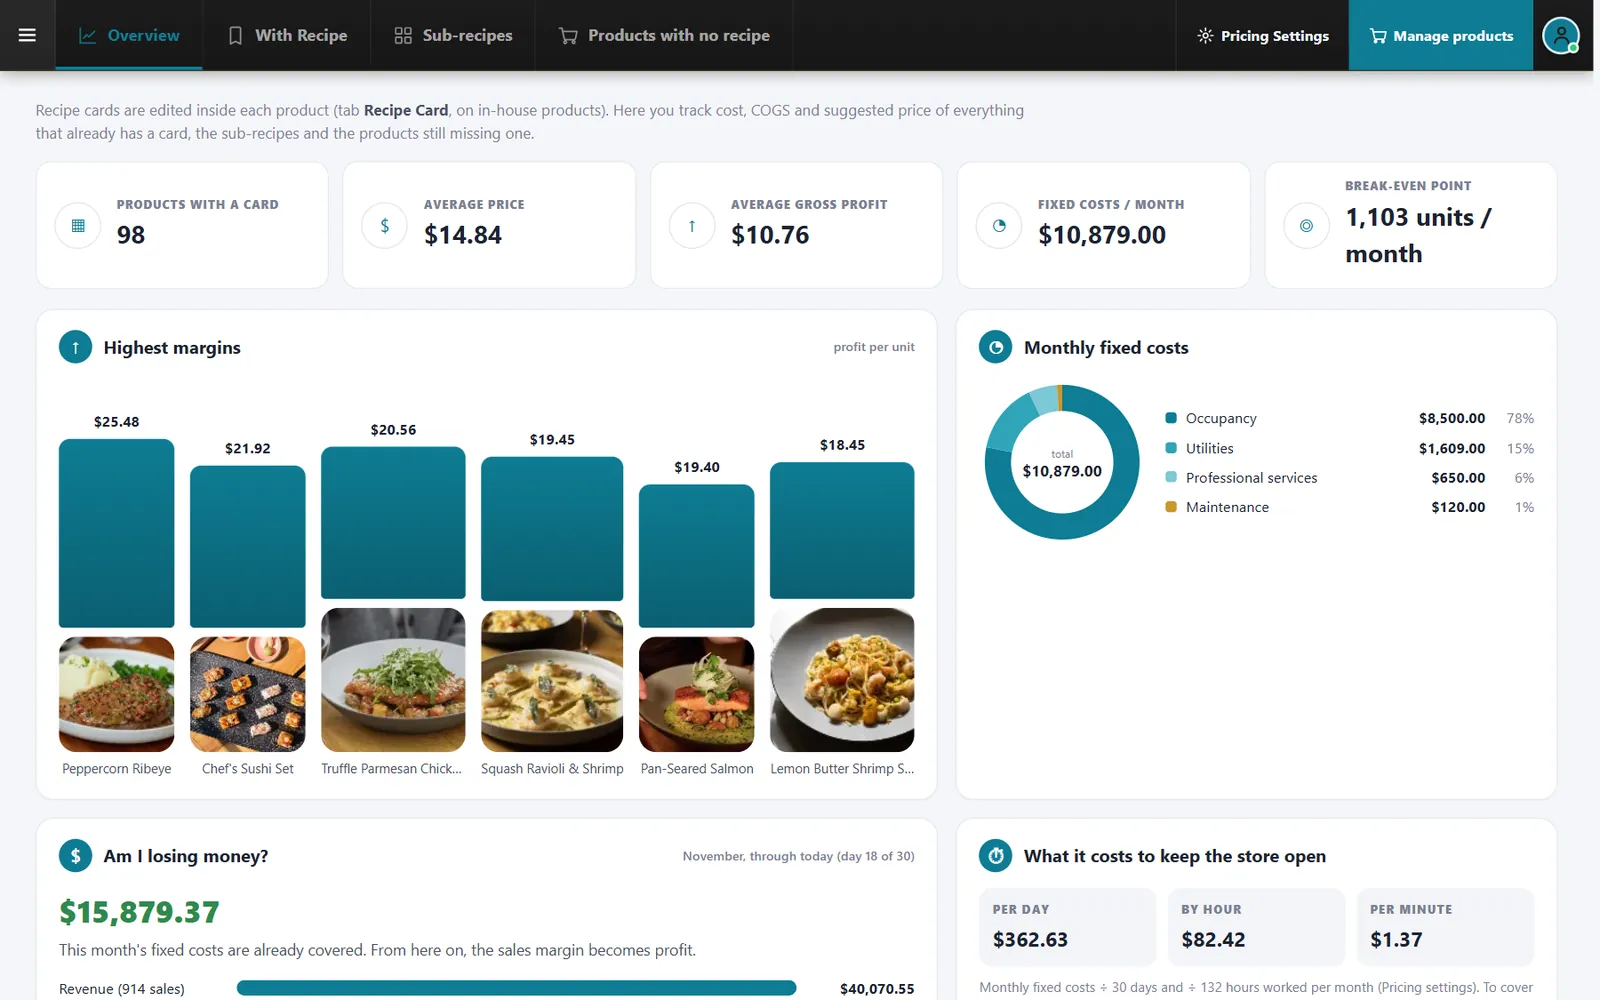
If you want your operating records connected to the same system, CounterChef runs on iPad, Android tablet, iPhone and computer. Inventory and recipe costing show the cost of each dish, and reports can be reviewed by day, item and employee.
The value of maintaining current costs is simple: your decisions are based on the food you're actually purchasing and serving, not on a recipe that was accurate several months ago.